Lender Spotlight / Agent Education
Rates are moving fast, and a major change is coming to the way homes are appraised. I sat down with Nolan Hartsock, Loan Officer with VanDyk Mortgage, to talk about a loan program worth understanding right now, a free appraisal event coming up on Thursday, October 15, and where mortgage rates may be headed.
RSVP for the Appraisal Lunch and Learn
Loan program highlight: temporary buydowns
Neal: Nolan, rates have been climbing quickly. What loan program should agents and buyers be paying attention to right now?
Nolan: Temporary buydowns. With rates increasing fast right now, getting a temporary buydown can be helpful. Whether it's one year or multiple, it can make homeownership an easier journey.
Neal: Where do buyers get tripped up?
Nolan: When talking with clients, oftentimes they get distracted by the lower payment. You want to make sure they understand what the rate will be once you lock it in. That is the worst case scenario long term if they don't refinance, and you want to make sure they don't get caught by surprise.
How a temporary buydown works
A temporary buydown lowers the interest rate for the first year or first few years of the loan. The cost is paid up front, often through a seller or builder concession. In a common 2-1 buydown, for example, the rate is 2 percentage points below the locked rate in year one, 1 point below in year two, and then the full locked rate from year three on. A 1-0 buydown covers just the first year.
The key is what Nolan described: the lower payment is temporary. The locked rate, and the payment that comes with it, is what the buyer should plan for long term.
Agent tip: when a buydown is on the table, put two numbers side by side for your clients: the year-one payment and the full-rate payment. If the full-rate payment works for their budget, the buydown is a cushion, not a gamble.
Upcoming event: appraisals are changing
Neal: Let's talk about the event. What's changing with appraisals?
Nolan: The way appraisals are being done is changing. Big time. We're bringing a real appraiser in to go over what impacts it will have, how to prepare, and what to expect.
Watch Neal and Nolan explain the appraisal changes and the October 15 lunch and learn.
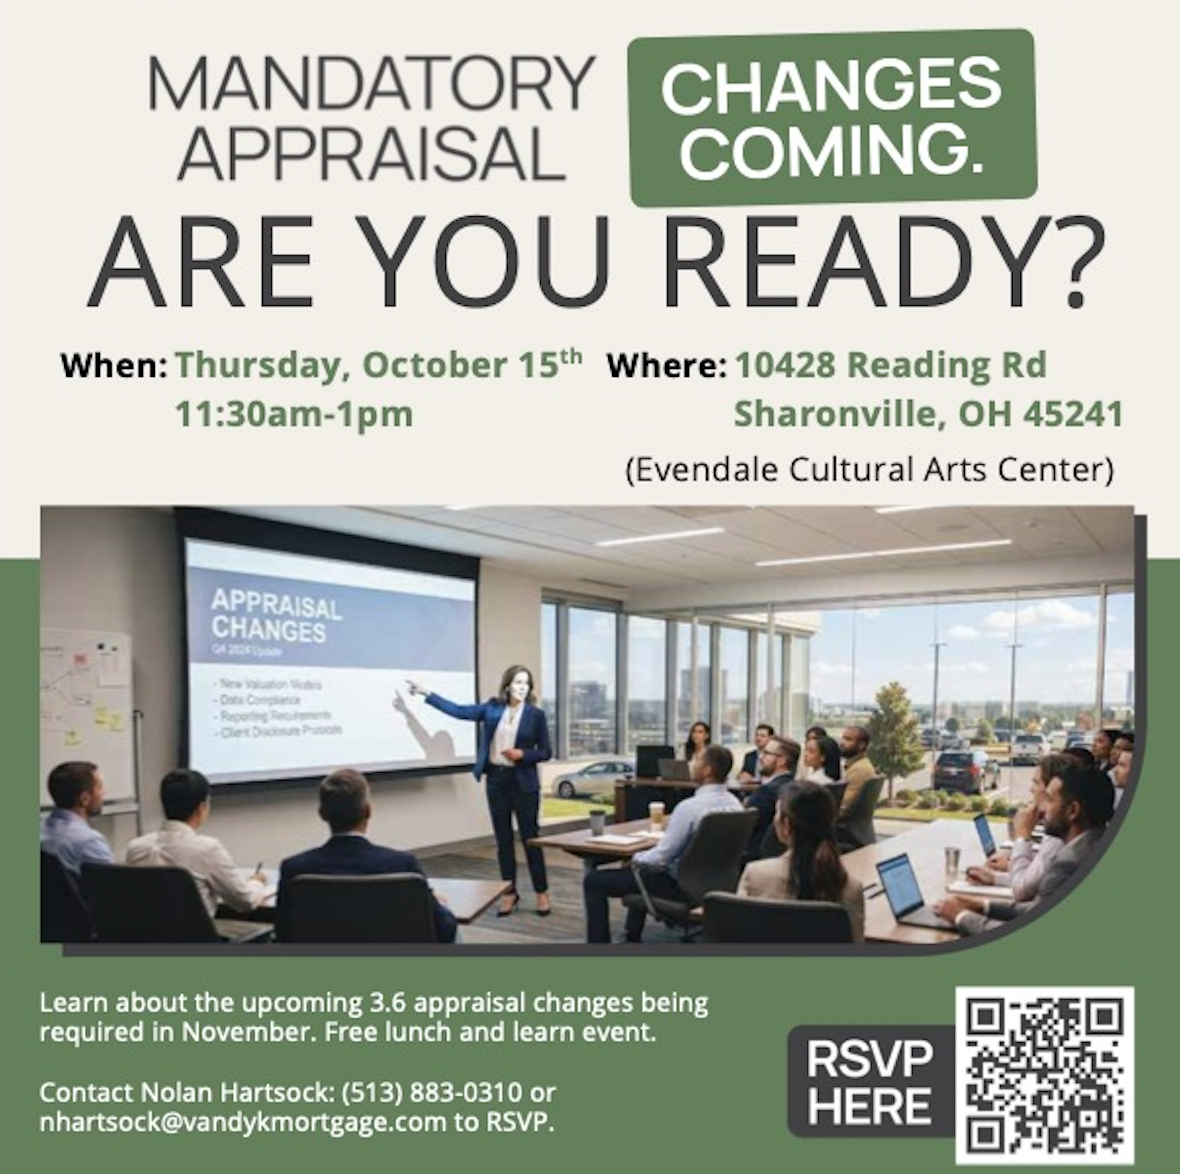
The session covers the upcoming 3.6 appraisal changes being required in November, widely known as UAD 3.6, the update to the Uniform Appraisal Dataset. As Nolan explains in the video, appraisals are moving from about 60 data points to 300. If you work with buyers or sellers who are financing, this affects your deals, so it is worth an hour over lunch to hear it directly from an appraiser.
Free Lunch and Learn
Mandatory appraisal changes are coming. Are you ready?
- When: Thursday, October 15, 2026, 11:30 AM to 1:00 PM
- Where: Evendale Cultural Arts Center, 10428 Reading Rd, Sharonville, OH 45241
- Cost: Free, lunch included
- Hosted by: VanDyk Mortgage, with Maronda Homes
Or RSVP with Nolan Hartsock: (513) 883-0310 or nhartsock@vandykmortgage.com. Please note this is not a CE class.
Where rates may be headed
Neal: Last question. What are you watching on rates?
Nolan: We're hoping the inflation data comes back in our favor for lower mortgage rates next week.
Rates can move daily, so if you have buyers on the fence, now is a good time to connect them with a lender who can walk them through their options, including whether a temporary buydown makes sense.
Connect with Nolan
Nolan Hartsock, Loan Officer, VanDyk Mortgage
Mobile: (513) 883-0310
Email: nhartsock@vandykmortgage.com
Questions about buying or selling? Contact Neal Mitchell and the Real Deal Home Team at Keller Williams Pinnacle Group at 513-301-9696.
Nolan Hartsock, NMLS #2680686. VanDyk Mortgage Corporation, NMLS #3035, nmlsconsumeraccess.org. Equal Housing Opportunity. This post is for general information only and is not a commitment to lend, a loan approval, or financial advice. Rates, terms, and program availability change frequently and are subject to borrower qualification. Temporary buydown terms and costs vary by loan program. Real Deal Home Team and Keller Williams Pinnacle Group are not mortgage lenders.